How Do Deepfakes Get a High-Value Payment Approved?
They supply the one thing approval processes still trust: a familiar face or voice confirming the request. FinCEN's alert FIN-2024-Alert004 (13 November 2024) notes that criminals have impersonated executives and trusted employees with GenAI tools to instruct victims to transfer large sums, and its sources include the case reported in February 2024 in which a finance worker paid out $25 million after a video call with a deepfake chief financial officer. The FBI's public service announcement I-120324 (3 December 2024) describes criminals generating video for real-time chats with supposed company executives.
The deepfake rarely works alone. It sits on top of a compromised mailbox, a lookalike domain or a researched org chart, and it targets the moment when an approver is asked to make an exception: skip a callback, approve outside normal hours, or release before the second approver is available. Controls that hold under urgency stop it; controls that bend for a convincing voice do not.
Bind Approval to the Final Payment, Not the Request
Many high-value losses pass through a real approval. The approver saw an invoice, an email or a call and agreed, but the payment released carried a different beneficiary or account. The fix is to make the approval screen show the exact fields being released (beneficiary name, account, bank, amount, currency, purpose) and to invalidate the approval if any of those fields change afterwards.
Separate the roles. One person or system initiates, a second person with the right entitlement approves the final data, and release happens once, under controlled credentials, followed by reconciliation of the bank's acknowledgement. Hash or otherwise fingerprint any attached invoice so a swapped file is visible.
Compare each payment with the history of the account and the beneficiary as well. A first payment to a beneficiary, an amount just under an approval threshold, a request outside business hours or a sudden change of destination country are each reasons to raise the approval tier. Write those triggers down, so an approver who escalates is following policy rather than second-guessing a senior colleague.
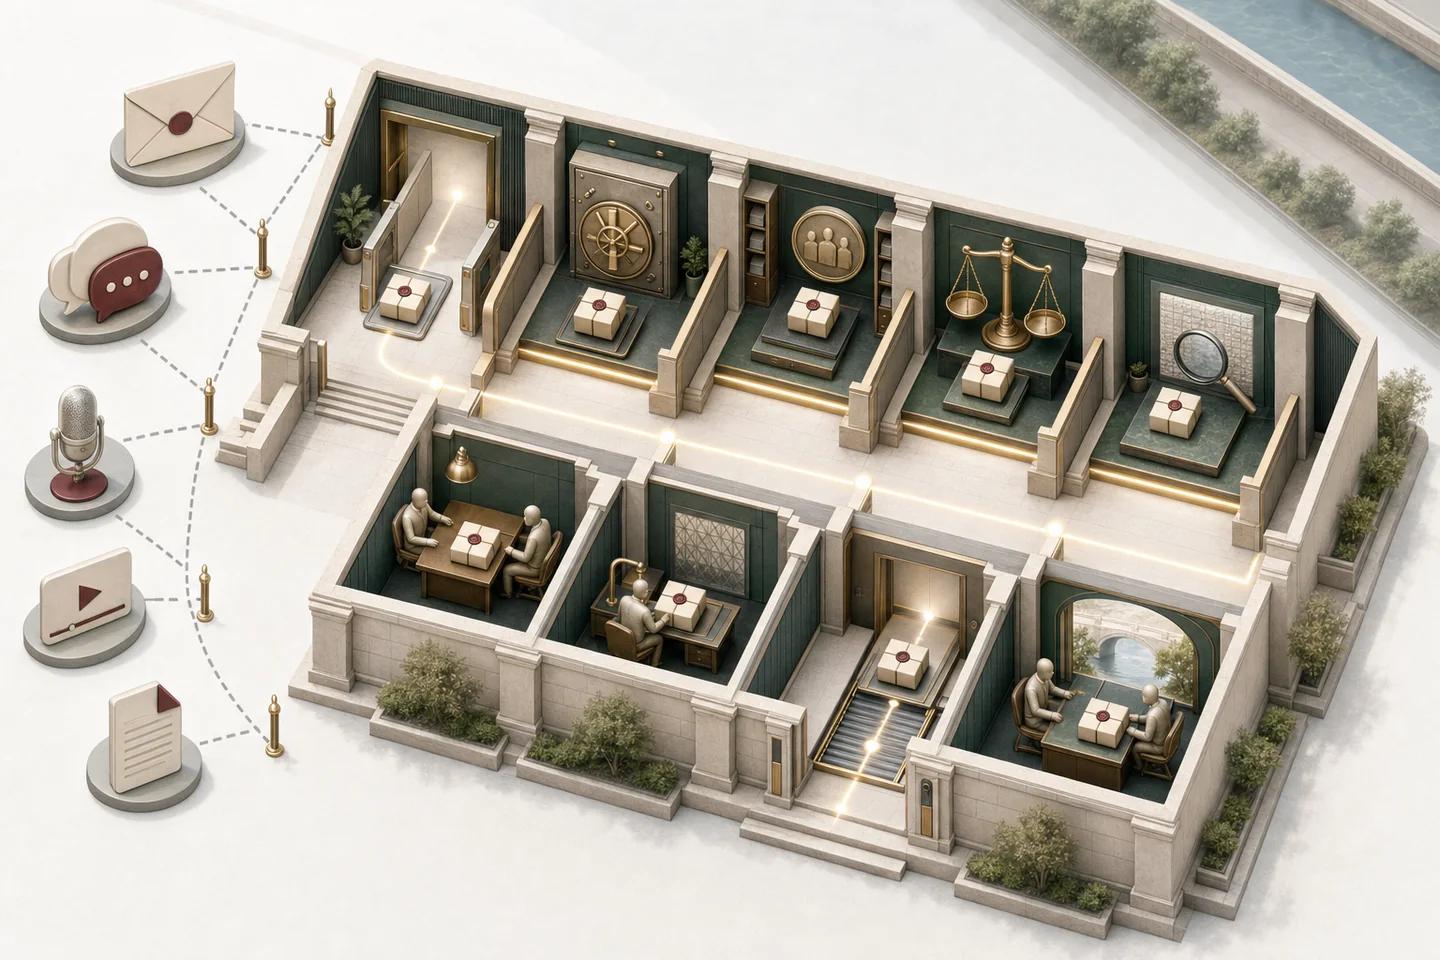
| Step | Control | Fails when |
|---|---|---|
| Initiation | Payment created from an approved source system or template | Instruction typed from an email or chat |
| Beneficiary check | New or changed account confirmed through payee verification and a callback to an on-file number | Callback uses the number in the request |
| Approval | Second person approves the final fields with step-up authentication | Approver sees only a summary or approves on a call |
| Release | Single release, logged, with limits by entitlement | Same person can edit and release |
| Reconciliation | Bank acknowledgement matched to the approved record | Returns and rejections handled outside the workflow |
How Should Finance Teams Verify Payment Requests Made on Video Calls?
Treat the video call as a request, never as the approval, and verify it through a different channel you already control. End the call, look up the requester's number in your own directory or contract records, call them back, and confirm the beneficiary, amount and reason. Then run the payment through the normal maker-checker path with no shortcuts because the request came from a senior person.
Set this expectation in policy before an incident, so that staff are not asked to challenge a CFO on the spot. A pre-agreed rule that no executive can waive dual approval or callbacks by phone or video removes the social pressure that deepfake callers rely on. If a recording or clip of the call exists, it can be checked for manipulation as supporting evidence, and kept for investigation if the request turns out to be false.
Why Repaired Cross-Border Payments Need a Fresh Approval
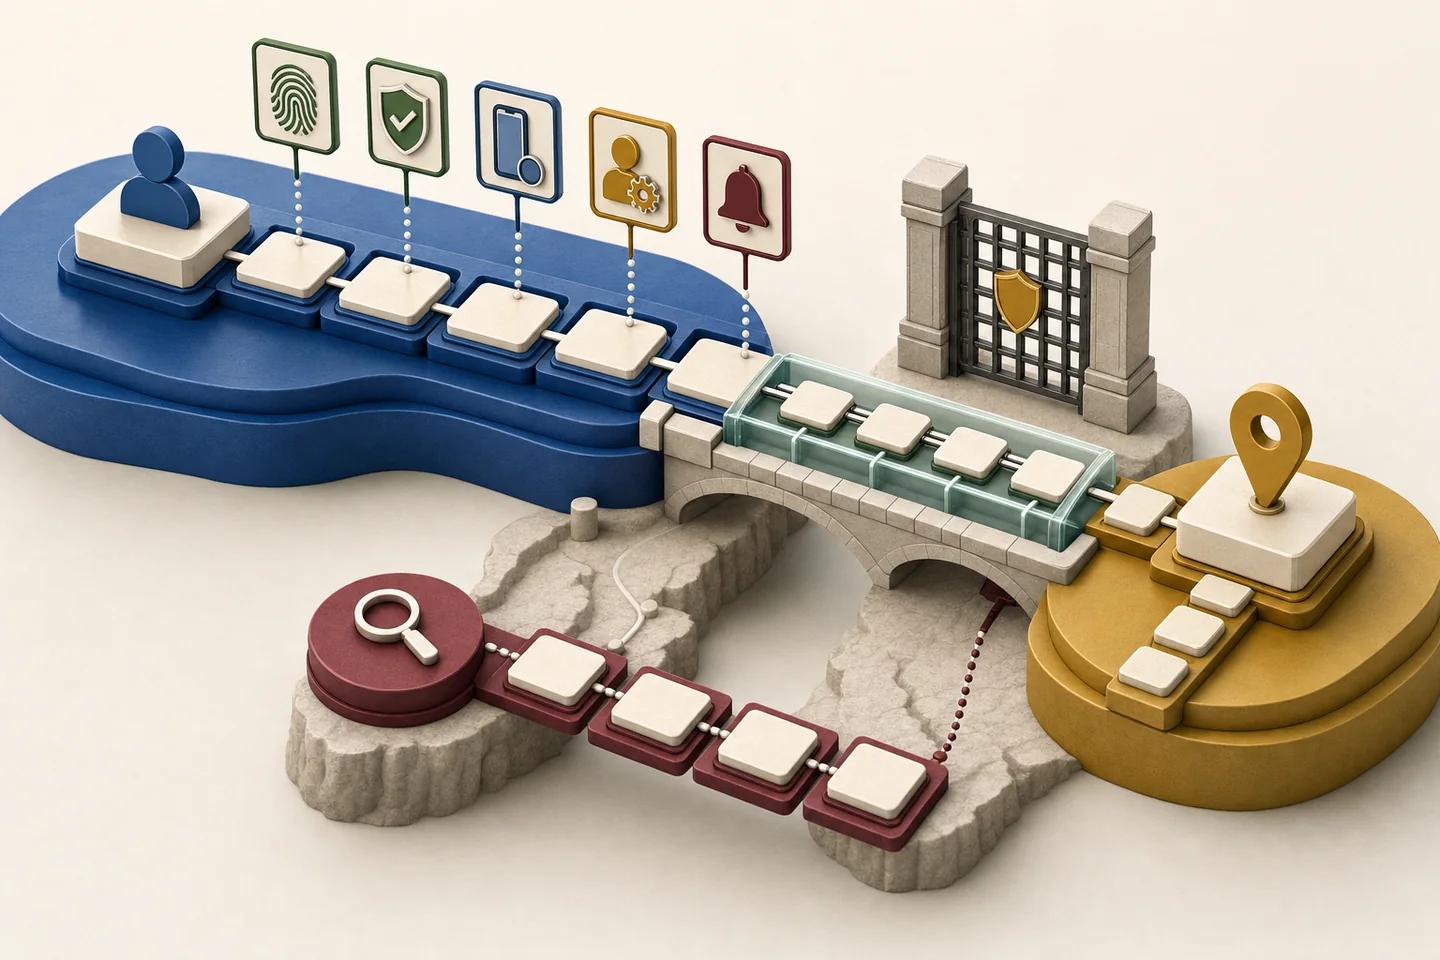
When a cross-border payment is rejected for incomplete or inconsistent data, someone corrects it. That repair can quietly change the beneficiary, bank or purpose, and urgent repair requests often arrive by unauthenticated email. Preserve the original message, record every field-level change with a reason code, obtain clarifications through authenticated interbank or customer channels, rerun sanctions and beneficiary checks after material changes, and require dual approval before the corrected instruction is released once.
Checking beneficiary data before money moves reduces both errors and fraud. The BIS Committee on Payments and Market Infrastructures, in CPMI Brief 9 (20 November 2025), describes payment pre-validation services that check payee names and account details before a cross-border payment starts, and says they can help mitigate authorised push payment fraud, while noting that cross-border adoption is still limited.
Where Neural Defend Fits in Payment Approval
NeuroVerify can score audio, video or a face image submitted in support of a high-value request, such as a voice note from an executive, a recorded call clip or a selfie step-up from an approver on a new device. One API call returns a unified risk score with evidence from six signals, including Face Manipulation Detection, AI Generative Model Analysis and Live Presence Verification. Eligible image requests return in under 200 ms at p95 under defined test conditions.
Neural Defend ranked first of 36 systems on the public VendorBench-100 still-image benchmark, with an MCC of 0.876 against 0.646 for the next vendor; one VendorBench author co-wrote Neural Defend's ARCAS 1B paper, and the corpus and results are public. The benchmark does not cover video or audio. When a payment has already gone and the recording becomes evidence, NeuroDetect builds a case with frame- and segment-level views and a downloadable forensic report. Neither product authorises a payment; the approval policy does.
What to Do in the First Hours After a Fraudulent Release
Speed decides recovery. The FBI's 2024 IC3 Annual Report says its Recovery Asset Team acted on 3,020 Financial Fraud Kill Chain complaints with $848.4 million in attempted losses and froze $469.1 million domestically and $92.5 million internationally, a 66% success rate. Most of those incidents began as business email compromise. Call your bank's fraud line, request a recall of the wire, report to IC3, and preserve the instruction, approvals and any audio or video involved.
Detection limits apply throughout. A clean manipulation score does not prove the requester was authorised, and a real executive can be coerced or mistaken. The approval record, not the media, is what shows whether the control worked.
Evidence boundary
Limitations
- Media screening only helps when audio or video is part of the request; many high-value frauds use email and documents alone.
- A genuine executive can give a fraudulent instruction under coercion or deception, and media checks will not flag it.
- VendorBench-100 measures still-image detection only and shares an author with the ARCAS 1B paper; video and audio performance should be tested in a pilot.
- Recall and recovery outcomes depend on the payment rail, jurisdiction and speed of reporting; nothing here guarantees recovery.
Source record
Sources and references
- Financial Crimes Enforcement NetworkFinCEN Alert on Fraud Schemes Involving Deepfake Media Targeting Financial Institutions (FIN-2024-Alert004)Published November 13, 2024. Verified October 19, 2026.
- FBI Internet Crime Complaint CenterCriminals Use Generative Artificial Intelligence to Facilitate Financial Fraud (PSA I-120324)Published December 3, 2024. Verified October 19, 2026.
- FBI Internet Crime Complaint Center2024 IC3 Annual ReportVerified October 19, 2026.
- Bank for International Settlements, CPMISafety and efficiency through payment pre-validation: spotting issues before money moves (CPMI Brief 9)Published November 20, 2025. Verified October 19, 2026.
- arXivVendorBench-100: A Unified Cross-Paradigm Benchmark for Deepfake Image DetectionPublished July 7, 2026. Verified October 19, 2026.